Singapore’s 6 GW Power Import Plan: 11 Projects, 4,200 km Cables, and the ASEAN Grid Bet
From Gas Island to Grid Hub: The 45% Import Target
Singapore generates about 95% of its electricity from natural gas, and the power sector contributes roughly 40% of national carbon emissions. With land too scarce for utility-scale solar and peak demand exceeding 8 GW, the city-state has turned outward. By September 2024, the Energy Market Authority raised its power import target from 4 GW to 6 GW by 2035—equivalent to approximately 45% of projected local electricity demand.
The 11 Conditional Approvals
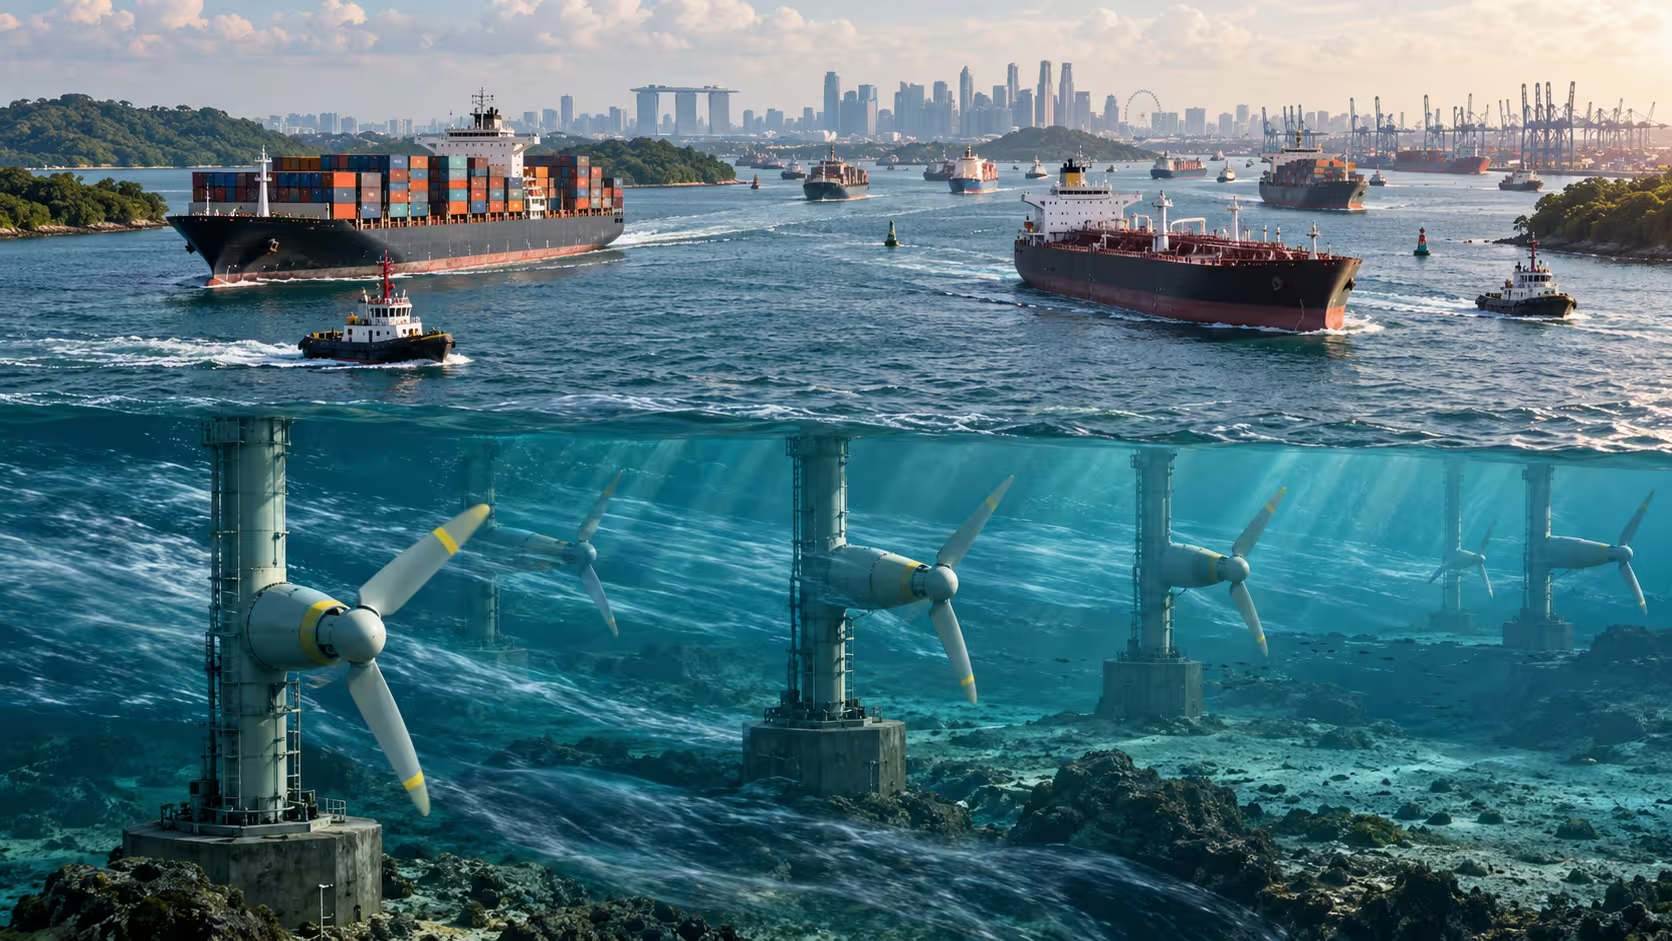
To date, EMA has issued conditional approvals to 11 projects to import low-carbon electricity from Australia, Cambodia, Indonesia, Sarawak in Malaysia, and Vietnam. Six projects have progressed to conditional licences. These projects will transmit a mix of solar PV, hydropower, and wind power through high-voltage AC or DC subsea cables.
The most ambitious is a 1.75 GW solar import from Australia’s Northern Territory via HVDC subsea cables spanning over 4,200 km—one of the longest proposed undersea power links in the world.
The ASEAN Power Grid Anchor Effect
Singapore’s import demand could serve as a commercial anchor for the broader ASEAN Power Grid. According to the Singapore Sustainable Finance Association, long-term export demand from Singapore may help underpin renewable energy development in Indonesia’s Riau Islands, potentially generating about US$4.2 billion in foreign exchange earnings and US$210 million in annual tax revenue for Indonesia.
For Sarawak, Singapore’s demand provides an additional market for surplus hydropower. The credit quality of Singapore-based electricity buyers—EMA-licensed entities and major energy players—could improve project bankability by lowering the cost of capital.
The Financing Gap
Demand alone is not enough. SSFA noted that unclear risk allocation, unresolved regulatory frameworks, and uncertain revenue assumptions could raise financing costs or prevent projects from reaching financial close. Regulatory hurdles have already led to delays, with a Wood Mackenzie report forecasting that Singapore may fall short of its 6 GW target by 2035.